- November 9, 2026
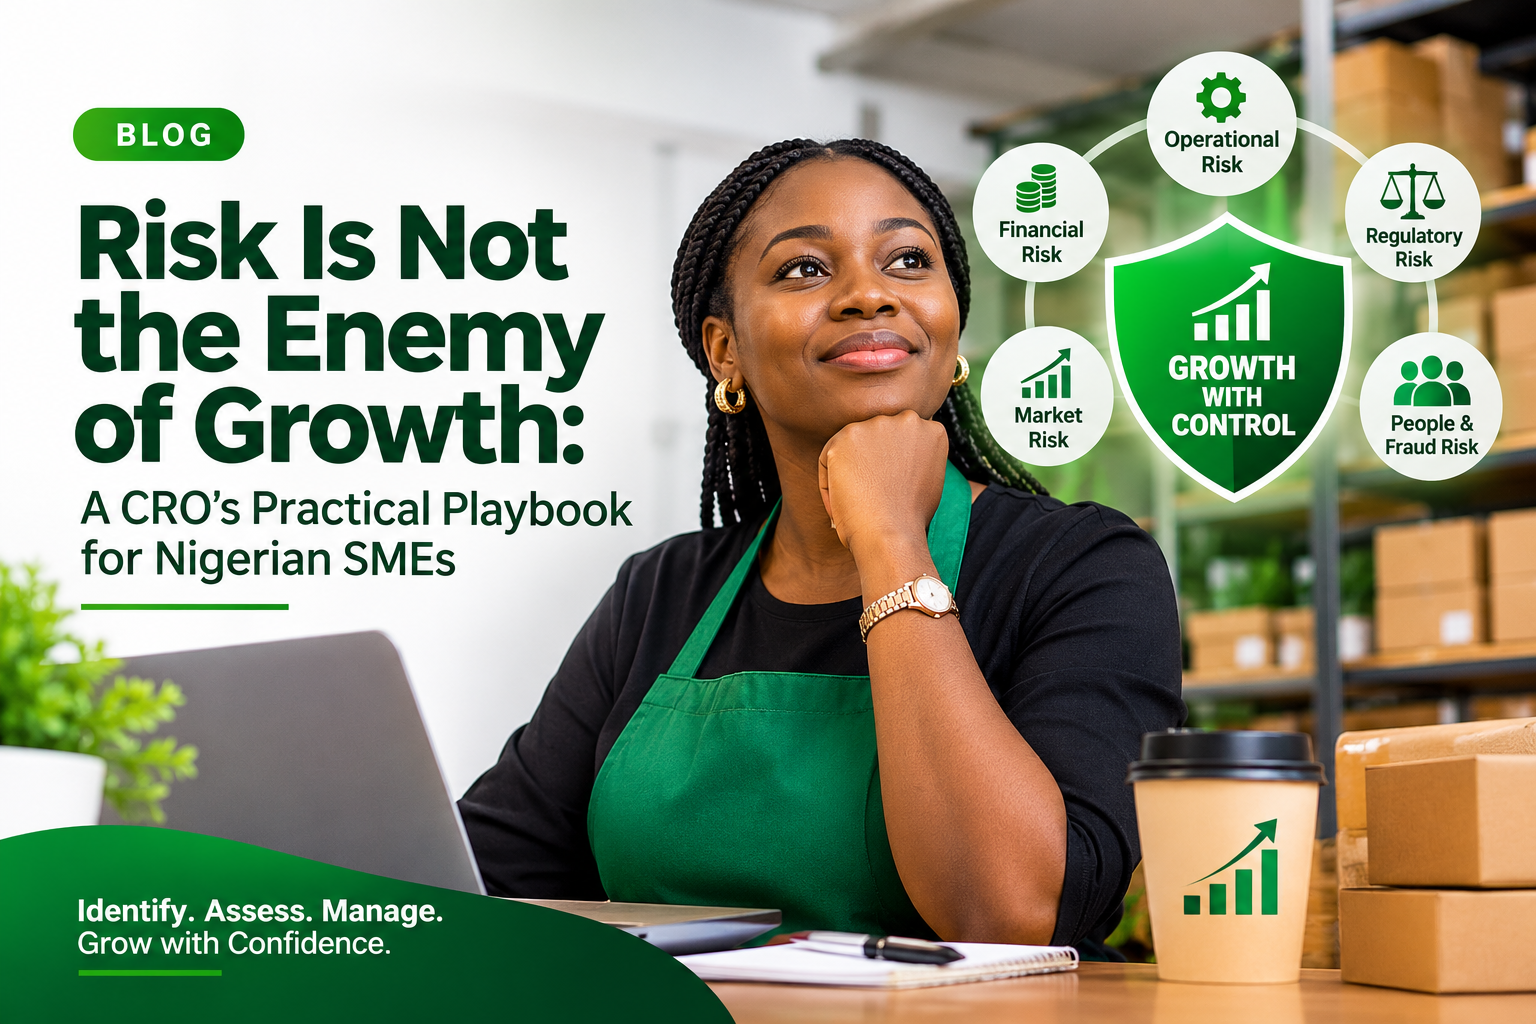
Many SMEs do not fail because they take risks; they fail because they do not identify and manage them early. As a Chief Risk Officer, my work centres on helping a business understand the risks it takes, assess their potential impact and put practical controls in place before they become losses. The same discipline is useful to every business, regardless of size.
Risk management does not have to mean thick manuals or committees. ISO 31000 provides a framework that organizations of any size or sector can apply: identify risks, assess their likelihood and impact, decide how to manage them, and monitor whether the controls are working.[1] For an SME, this can be as straightforward as maintaining a short risk register, reviewing cash flow regularly and assigning clear responsibility for key controls.
Cash shortages, weak working-capital management, excessive borrowing, rising costs and customer defaults can threaten a business even when its accounts show a profit. Selling on credit is a form of lending: every unpaid invoice ties up cash and creates exposure. Check customers’ payment history, set credit limits, document payment terms and monitor receivables aging. Also watch customer concentration; where one customer accounts for a significant share of sales, a delayed payment can quickly become a liquidity problem. Monitor cash flow, debt obligations, operating expenses and available liquidity. PwC’s 2024 MSME Survey, which covered 557 MSME operators across 13 sectors and 29 states, identified inadequate access to finance as the leading growth challenge, cited by 35% of surveyed businesses.[2]
Power outages, equipment failure, supplier disruption, inventory losses, weak processes and technology downtime can interrupt service and revenue. The World Bank’s 2025 Enterprise Survey for Nigeria indicates that approximately 82% of firms surveyed experienced electrical outages; the sample covers firms of all sizes, not only SMEs.[3] Identify critical processes, arrange backup power where viable, maintain essential equipment, identify alternative suppliers and document recovery procedures. Avoid dependence on one person for passwords, supplier relationships or essential know-how: document key processes, cross-train staff and keep secure off-site or cloud backups.
Inflation, exchange-rate movements, changing customer preferences, new competitors and poorly assessed expansion plans can weaken margins or make a product uncompetitive. Monitor sales trends, customer feedback, competitor activity, input costs and pricing. Before committing funds to expansion, validate demand, test cost and revenue assumptions, assess operational capacity and consider downside scenarios. The PwC survey also identifies macroeconomic headwinds and changing market conditions as important business-sustainability considerations.[2]
Tax defaults, expired licenses, incomplete records, contractual breaches, employment disputes and data-protection failures can lead to penalties, litigation, reputational damage or business interruption. Maintain a compliance calendar covering applicable taxes, levies, licenses and filing dates; keep evidence of submissions and payments; use clear written contracts; and seek professional advice when necessary. Multiple taxes and levies are among the growth constraints that Nigerian businesses reported in the same survey.[2]
Weak supervision, unclear responsibilities, poor segregation of duties and excessive reliance on individuals create opportunities for fraud and operational errors. Cyber risks include phishing, unauthorized access, data loss and payment fraud. Set approval limits, restrict system access by role, independently reconcile accounts, verify changes to supplier bank details through a known contact, and require dual approval for sensitive payments. Use strong passwords and multi-factor authentication, train staff to recognize suspicious requests, and maintain tested data backups. Trust matters, but it must be supported by effective controls.
A risk register makes risk management actionable. It records the main exposure, the warning sign to watch, the control to apply, how often to review it and who is accountable. The examples below group related exposures into eight entries so that an SME can maintain a short, usable register.
| Key risk | Early warning indicator | Practical control | Review | Owner |
| Cash flow and customer credit | Overdue invoices, rising receivables or a cash forecast unable to cover near-term obligations. | Maintain a rolling 13-week cash forecast; check customers’ payment history; set credit limits and payment terms; follow up overdue balances. | Weekly | Finance / Sales |
| Debt and concentration | Debt repayments absorb more cash; one customer or funding source represents a material share of exposure. | Match borrowing tenor to cash generation; approve new debt; set concentration limits and diversify customers/funding. | Monthly | Finance / Management |
| Operating continuity | Repeated outages, equipment faults, missed service targets or reliance on one key person. | Plan backup power; maintain critical equipment; document essential processes; cross-train deputies and keep secure backups. | Monthly | Operations |
| Supplier and inventory disruption | Late deliveries, stock-outs, unexplained stock variances or dependence on one supplier. | Qualify alternatives; monitor supplier performance; maintain stock records; conduct periodic counts and investigate variances. | Monthly | Procurement / Operations |
| Market, cost and expansion decisions | Falling sales or margins, changing customer demand, rising input costs or expansion assumptions not being met. | Review customer feedback, pricing and unit costs; validate demand and cash-flow assumptions before expansion commitments. | Monthly; before investment | Sales / Management |
| Regulatory, tax and contractual compliance | Missed filing or renewal dates, incomplete records, unresolved notices or unclear agreements. | Maintain a compliance calendar; retain evidence of filings and payments; use written contracts and obtain advice where needed. | Monthly | Finance / HR / Legal |
| Fraud and payment diversion | Unexplained cash differences, unusual transactions or urgent requests to change supplier bank details. | Segregate duties; set approval limits; reconcile independently; verify bank-detail changes using a known contact; require dual approval. | Monthly; every payment-detail change | Finance / Operations |
| Cyber, data and access risk | Suspicious logins, phishing attempts, failed backups or inaccessible business records. | Apply role-based access and multi-factor authentication; train staff; update devices; back up data and test restoration. | Monthly | IT support / Operations |
When you set up your own register, add columns for likelihood, impact and overall score. Score each risk for likelihood and impact on a scale of 1 to 5, then multiply the two to get the overall score. Address the highest scores first. Review the register monthly, update it when circumstances change and ensure every action has one accountable owner. A register that is not reviewed is only paperwork.
Daily: Check the cash position, urgent customer complaints, pending approvals and unusual staff or account activity.
Weekly: Review the 13-week cash forecast, overdue receivables and the most significant operational blockers.
Monthly: Review the risk register, management accounts against budget, compliance calendar, supplier performance and staff capacity.
Quarterly: Test business-continuity arrangements; review pricing, margins and customer, supplier and product concentration; re-forecast the next 12 months.
Annually: Refresh key policies, review records, insurance and contracts, and reassess key-person dependencies.
Track a small number of useful indicators rather than dozens: days sales outstanding, cash runway in weeks, on-time delivery or service rate, complaint-resolution time and the percentage of revenue generated by the largest customer. These measures help management spot pressure early and act before it becomes a loss.
Days 1–30: Establish visibility. Map the main business activities; identify and record the ten most significant risks; prepare a 13-week cash forecast; and confirm the business’s tax registration, tax status and filing dates.
Days 31–60: Put controls in place. Assess each risk’s likelihood and impact, priorities the most significant exposures and assign accountable owners. Introduce practical measures such as payment approval limits, customer credit limits, documented critical processes and secure off-site backups.
Days 61–90: Test and improve. Begin regular risk reviews and track early-warning indicators. Cross-train staff, agree the funding plan for the next year, test a continuity scenario such as the loss of a key supplier, and escalate unresolved control gaps to management.
CreditPRO Finance Company Limited began as a business support services company and became a CBN-licensed finance company in September 2025.[4] Responsible lending is a core commitment, supported by dedicated risk management, compliance and internal control functions.[4] We believe that responsible finance starts with understanding whether a business can convert funding into sustainable growth.
Our financing solutions are designed around different business needs. Working capital finance supports short cash-cycle gaps, with repayment periods of 30 to 180 days.[5] Invoice discounting provides access to cash against unpaid invoices from reputable corporate and government customers.[6] Revenue-based financing links repayments to a percentage of future revenue and may suit businesses that face challenges with traditional collateral.[7] Our loan calculator helps applicants estimate monthly repayments, total interest and upfront fees before applying,[8] while our financial advisory service supports funding readiness, cash-flow management and working-capital strategy.[9]
Businesses seeking to strengthen their risk map or assess their funding readiness can contact CreditPRO through www.creditprosme.com.
Risk is an unavoidable part of doing business in Nigeria. Businesses that grow sustainably are not those that avoid every risk, but those that identify exposures early, understand their consequences and apply controls proportionate to the threat. You do not need a dedicated risk department to begin. Start with a concise register, a regular review routine and clear accountability. This week, take one practical step: prepare a cash forecast, set a payment-approval limit or put compliance dates in a shared calendar. Consistent action protects cash, customer trust and access to finance.

About the Author
Olabisi Omotayo is the Chief Operating Officer at CreditPRO Finance Company Limited, where she plays a key role in strengthening operational efficiency, credit management and business performance. With experience in loan portfolio management, risk oversight and financial operations, she is committed to driving operational excellence, strengthening institutional processes and promoting responsible lending practices that support sustainable business growth. You can reach her on LinkedIn