- October 28, 2026
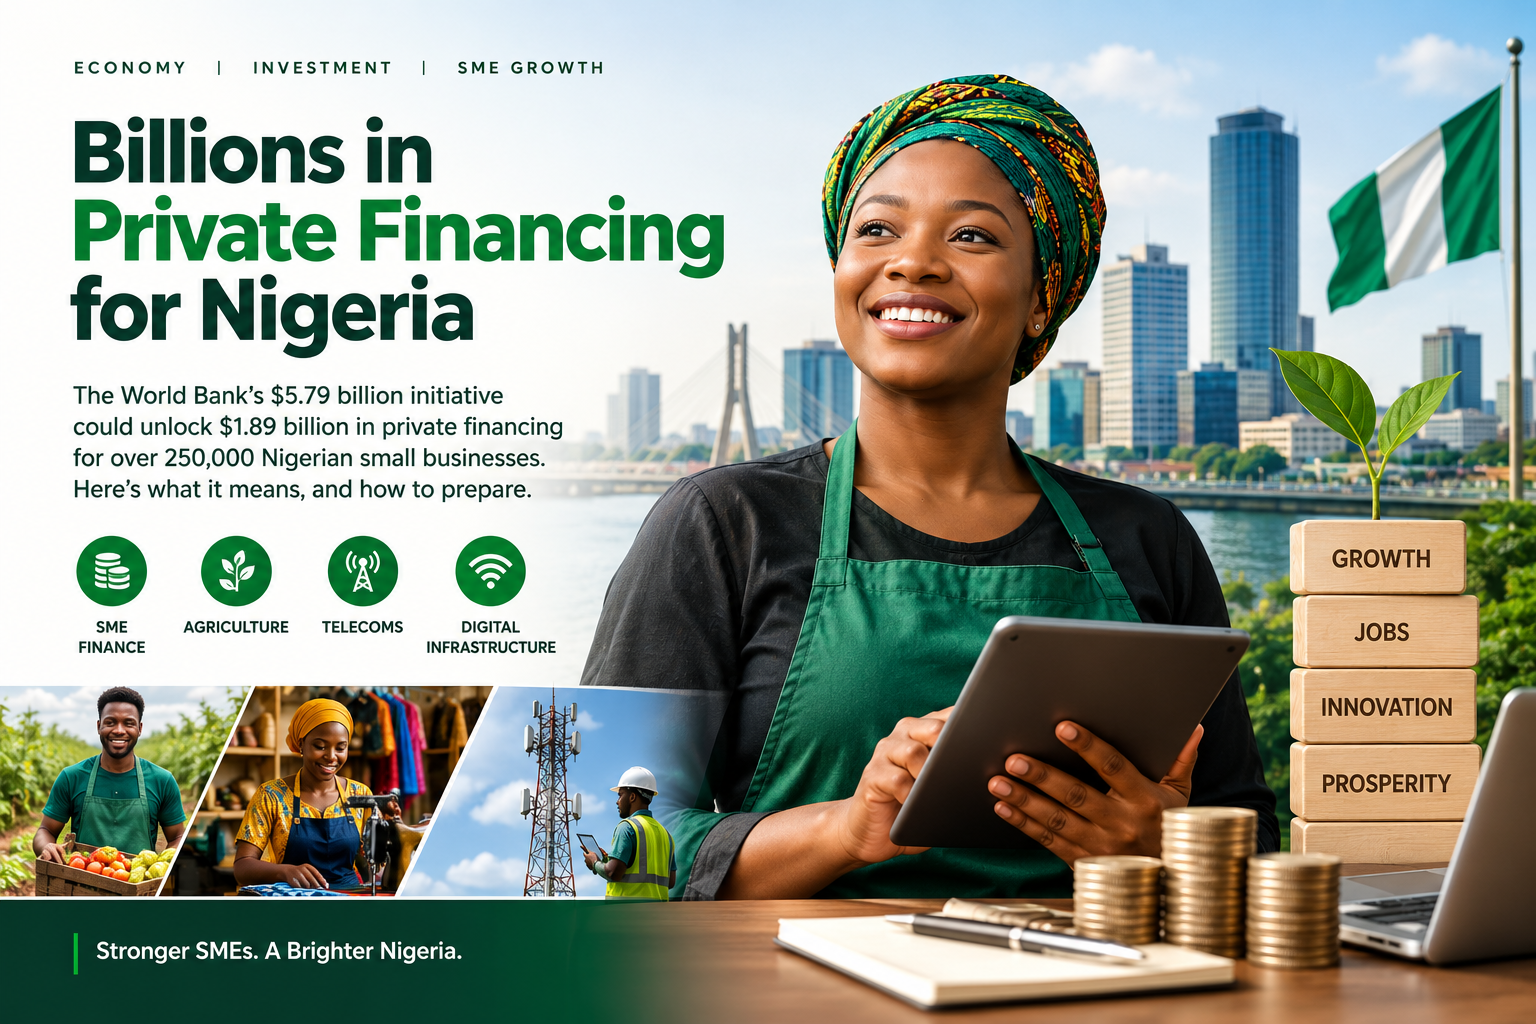
The initiative could mobilize nearly $1.89 billion in private financing for more than 250,000 Nigerian small businesses but entrepreneurs must prepare to access the opportunities.
Nigeria’s small and medium sized enterprises (SMEs) may be heading towards a significant financing opportunity as the World Bank Group moves to mobilize up to US$5.79 billion in private financing for Nigeria during fiscal year 2026.
Announced in a report on October 11 2026, the initiative targets critical sectors including small business finance, agriculture, telecommunications and digital infrastructure. It combines investment projects, commercial financing, policy reforms and risk sharing arrangements designed to attract private investors into Nigeria’s economy.
For SMEs struggling with expensive loans, inadequate working capital and limited access to expansion finance, one component stands out here which is the Fostering Inclusive Finance for MSMEs in Nigeria (FINCLUDE) programme.
What Is Available for Small Businesses?
FINCLUDE is backed by a US$500 million World Bank financing package and is expected to mobilize approximately US$1.89 billion in private capital. According to the World Bank, the programme aims to expand debt financing to more than 250,000 micro, small and medium sized enterprises including at least 150,000 women led businesses and 100,000 agribusinesses. It also plans to provide up to US$800 million in credit guarantees to encourage lenders to finance businesses they might otherwise consider too risky.
The programme is expected to support approximately 850,000 direct and indirect job and it also seeks to extend the average maturity of MSME loans to around three years thereby giving eligible businesses more time to invest in equipment, production capacity and expansion.
However, the US$1.89 billion represents expected private financing to be mobilized through the programme which means that it is not a grant pool available for entrepreneurs to share directly. Access will depend on programme implementation, participating financial institutions, eligibility criteria and lenders’ assessment of individual businesses.
Beyond SME Loans: Other Opportunities
The wider US$5.79 billion initiative also targets sectors that support small business growth.
In agriculture, the Agricultural Value Chains for Growth project aims to support one million smallholder farmers and mobilize approximately US$242 million from agribusiness firms and certified seed producers and this could create opportunities for agricultural input suppliers, processors, transporters, storage operators and distributors.
In digital infrastructure, the BRIDGE project aims to expand broadband access to an additional 58 million people by 2030, potentially improving connectivity for businesses, digital entrepreneurs and online retailers.
These investments matter because SME growth depends not only on financing but also on reliable infrastructure, functioning supply chains, market access and technology.
From a business and financial management perspective, the most significant aspect of this initiative is its attempt to address one of Nigeria’s persistent business challenges which is the gap between SMEs that need financing and the financial institutions willing to lend to them.
The World Bank has reported that fewer than one in twenty MSMEs in Nigeria has access to bank credit, while collateral requirements, costly borrowing and short repayment periods continue to constrain businesses.
Credit guarantees can help reduce lenders’ exposure to risk and encourage financing for viable businesses. However, they do not eliminate the need for sound credit assessment, responsible borrowing or repayment.
The initiative will therefore be most valuable if it translates into accessible, appropriately priced financing for businesses that can use capital productively. Its success should be measured not simply by the amount announced, but by how much financing reaches eligible enterprises, the affordability of the loans, the businesses sustained and the jobs created.
What Should Nigerian SMEs Do Now?
Entrepreneurs should not wait until financing becomes available before preparing their businesses.
First, maintain accurate records of sales, expenses, inventory, debts and cash flow.
Second, separate personal finances from business transactions and use a dedicated business account where practical.
Third, formalize business operations and keep relevant registration and compliance documents up to date.
Most importantly, prepare a clear financing plan by identifying how much capital the business needs, what it will purchase, how the investment will increase revenue or productivity, and how the business will repay the loan.
For example, a food processing SME seeking equipment financing should be able to demonstrate existing demand, current production capacity, expected additional output, projected sales and the cash flow available to meet repayments.
SMEs should also monitor official announcements from the Development Bank of Nigeria and participating financial institutions for FINCLUDE implementation details, application procedures and eligibility requirements. The US$5.79 billion announcement should not be interpreted as an open application for every Nigerian SME.
Key Takeaway
The World Bank Group’s US$5.79 billion private financing initiative represents an important opportunity to expand investment in Nigeria’s businesses and productive sectors. Its FINCLUDE component is particularly relevant to SMEs because it aims to mobilize private capital, improve access to debt financing and encourage longer term lending.
Nevertheless, funding announcements do not automatically translate into accessible credit. Entrepreneurs must understand the requirements of lenders, demonstrate repayment capacity and show that borrowed capital will generate sustainable business value.
Not every SME will qualify for a grant or government backed financing programme so businesses should therefore strengthen their financial records and creditworthiness while exploring suitable private sector financing options.
The opportunity is significant but preparation will determine which businesses are ready to benefit.
For SMEs in Nigeria the priority is to become finance ready before the money arrives not after.
About the Author
Dr. Ozemoya Osikpemhi Amos Onoshoze Pedro is an accounting and finance scholar, researcher, and professional with over a decade of industry experience. Holding a Ph.D. in Accounting and Finance, his expertise spans corporate finance, strategic management, governance, and business innovation. He is passionate about producing research that bridges academic theory with practical business solutions, helping organizations achieve sustainable growth and financial excellence. You can reach him on LinkedIn