- October 28, 2026
The tax cliff every growing Nigerian SME must plan for before year-end
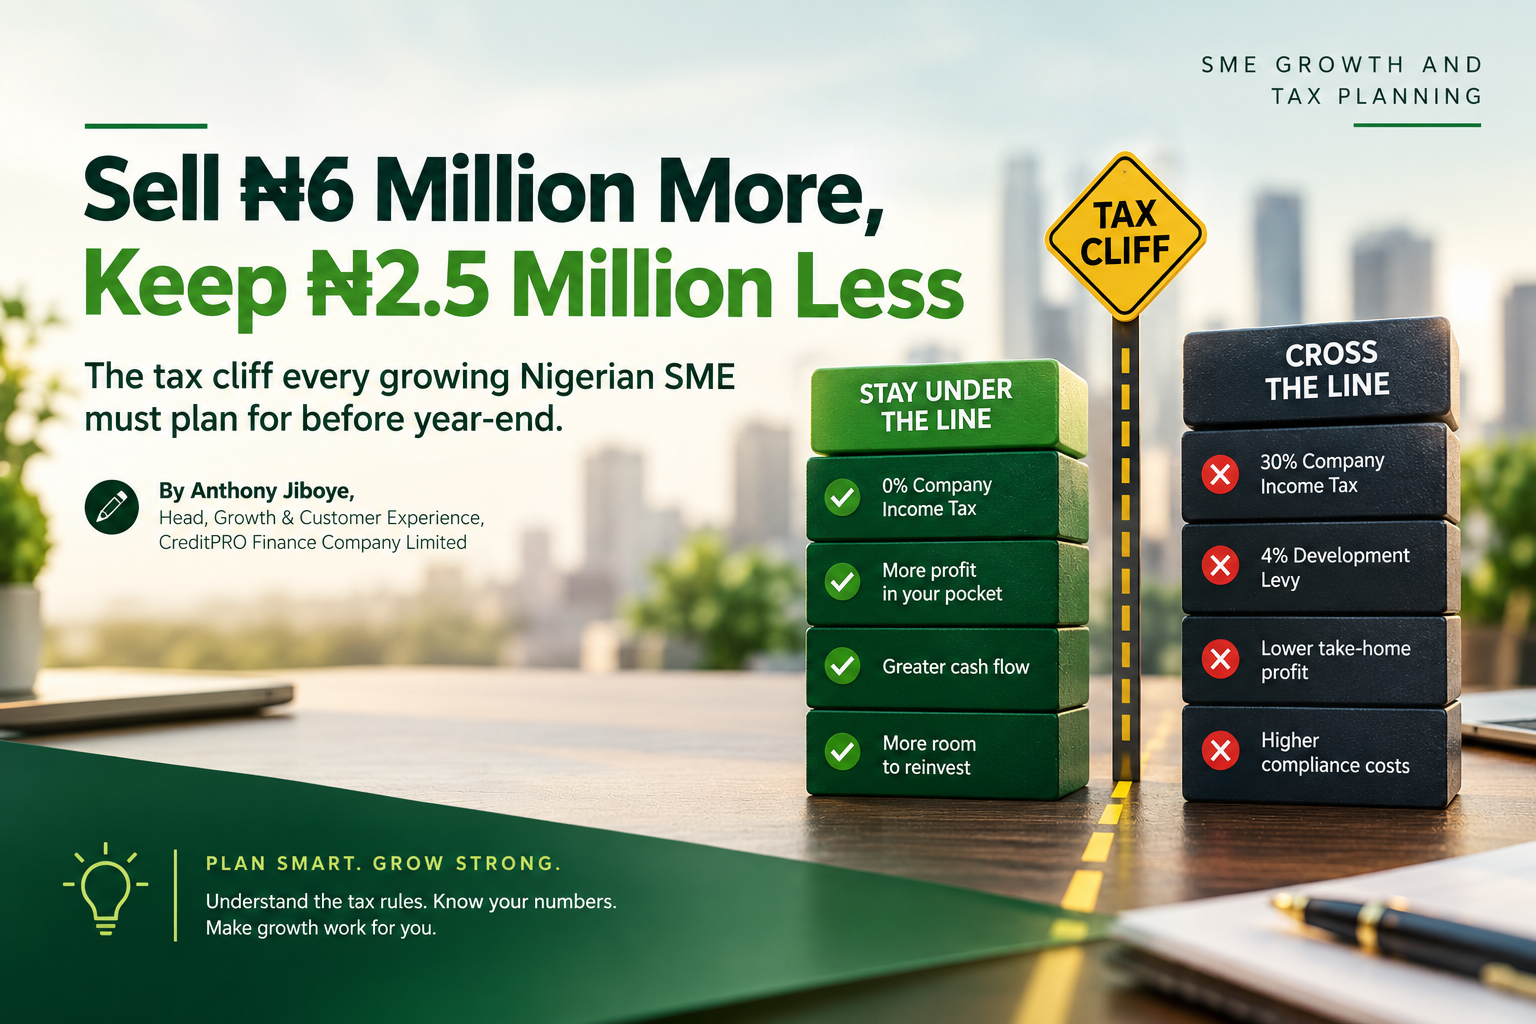
Amaka runs a catering company in Lagos. This year she sold ₦49 million and kept ₦9.8 million in profit, tax free.
Tunde runs an identical catering company, with the same kitchen, the same prices and the same margins. He pushed harder, closed ₦6 million more in sales, and took home about ₦7.3 million. That is roughly ₦2.5 million less than Amaka, for more work.
Nothing went wrong in Tunde’s business. What caught him is a feature of Nigeria’s new tax regime that few founders have priced in: the small company cliff. Qualifying small companies pay 0% company income tax. Cross the line, and the whole year’s profit is taxed, not just the part above it.[1][2][7]
Most guides treat this as a compliance checklist. This article treats it as what it really is for a growing business: a growth decision with a price tag. You will see the maths, a rule of thumb you can use today, and a simple way to decide whether to stay under the line, cross it on purpose, or find out first where the line actually sits.
S T A T S P O T L I G H T
A business sitting just under the line needs about 50% more revenue after crossing it to take home the same profit. At a ₦50 million line, that is roughly ₦76 million. At a ₦100 million line, roughly ₦152 million.
Assumes a constant profit margin, 30% company income tax and the 4% development levy on the same profit base. See the workings below.
What Happened?
Nigeria’s tax reform laws took effect on 1 January 2026. Three changes matter most to a growing SME:
Here is the part most articles skip. The gazetted Nigeria Tax Act (NTA) sets the small company turnover limit at ₦50 million, whereas an earlier harmonized draft had ₦100 million.[1][2] The companion Nigeria Tax Administration Act (NTAA) refers to a “small business” at ₦100 million, in a VAT context.[2] Many popular guides repeat the ₦100 million figure.[3]
Commentators describe the mismatch as unresolved, and as far as we could establish at 25 October 2026, no definitive official clarification has been published.[6]
Even a company that pays no tax must still register for a TIN, keep records that support its turnover and asset figures, and file annual returns. Late filing is penalized from ₦100,000 in the first month.[3]
The tax is charged on profit, but the cliff is triggered by turnover. That mismatch is what makes the cliff expensive. Here is Amaka and Tunde side by side, using the ₦50 million line and a 20% profit margin.
| Amaka (stays under) | Tunde (crosses) | |
| Annual turnover | ₦49.0m | ₦55.0m |
| Profit at 20% margin | ₦9.80m | ₦11.00m |
| Company income tax (30%) | ₦0 | ₦3.30m |
| Development levy (4%) | ₦0 | ₦0.44m |
| Profit after tax | ₦9.80m | ₦7.26m |
| Difference | ₦2.54m less |
Illustration only. It assumes assessable profit equals taxable profit and ignores capital allowances, losses and other adjustments your accountant would apply.
Because the whole profit becomes taxable, there is a stretch of growth where more revenue leaves you worse off. Call it the dead zone. It starts at the line and ends where your after-tax profit finally catches up with where it was before you crossed.
The maths is simple. After crossing, you keep about 66 kobo of every naira of profit (100% less 30% CIT less 4% levy). To end up where you started, profit must rise by 1 divided by 0.66, which is about 1.5 times. Because the line is set on turnover, the same 1.5x applies to revenue whatever your margin. For Tunde, the dead zone runs from ₦50 million to about ₦76 million. If the rate is ever cut to 25%, the combined 29% charge shortens the dead zone to roughly 1.4x.[4]
This is not an argument against growth. Revenue beyond the dead zone brings scale, bigger customers and more borrowing capacity, and many businesses should cross it. The point is to cross on purpose, with a plan to clear the dead zone, rather than drift over by accident in December.
There is also a lender angle. Repayment capacity is judged on cash left after tax. A business that jumps from 0% to a 34% combined charge on its profits can look quite different on paper the following year, even though sales went up.
| Zone | Annual turnover | What to do |
| Safe zone | Below ₦40m | Track turnover monthly and keep your records clean. |
| Watch zone | ₦40m to ₦50m | Model every new contract and equipment purchase before you sign. |
| Grey zone | ₦50m to ₦100m | The two Acts point to different lines. Get written advice on your company’s position and plan around the lower line until you have it. |
| Taxable zone | Above ₦100m | Full CIT and levy apply. Aim to grow clear of the 1.5x mark (about ₦152m) so the extra revenue pays for itself. |
Fixed assets matter too. A large equipment purchase can take you past the ₦250 million asset limit even when turnover is low, so check both tests.
When a business asks us for financing, the useful conversation starts with after-tax cash flow, not revenue. Owners who have already modelled where they sit on the small company map can tell us what a new contract does to their repayment ability, and that makes a yes much easier to give.
Before you chase the next large order, ask three questions: what will it do to my tax status, to my cash flow, and to my ability to repay? Then try the numbers in our loan calculator.[8] If you want a second pair of eyes, reach out to the CreditPRO team through our contact page.
Go back to Amaka and Tunde. Neither is wrong. Amaka chose the line and kept her profit. Tunde crossed it by accident and paid for it. Had he planned to reach ₦80 million, clearing the dead zone, he would have come out ahead of Amaka, with a bigger business to show for it.
The only losing move is drifting over the line without knowing it. Put two numbers on your management dashboard this week: your year-to-date turnover and your distance from the line, in naira and as a percentage. Then decide, with your accountant, which side of the cliff you want to be on.
https://assets.kpmg.com/content/dam/kpmg/ng/pdf/2025/07/Updates%20to%20the%20Nigeria%20Tax %20Act.pdf
(June 2025). https://www.pwc.com/ng/en/assets/pdf/the–nigeria–tax–reform–acts–top–20–changes–toknow–and–top–6–things–to–do–pwc.pdf
About the Author
Anthony Jiboye is the Head of Growth and Customer Experience at CreditPRO Finance Company Limited. With a proven track record in driving business expansion, customer retention strategies, and service excellence, Anthony leads CreditPRO’s growth initiatives to deliver seamless, customer-centric financial solutions. He is passionate about scaling innovative financial products, enhancing user journeys, and empowering businesses across Nigeria to access reliable funding and growth opportunities.