- September 16, 2026
Unlocking Homeownership Through the NHF Mortgage Loan: An SME Guide to Affordable Housing Finance
What is the National Housing Fund (NHF) Loan?
The National Housing Fund (NHF) Mortgage Loan is a government backed housing finance facility administered by the Federal Mortgage Bank of Nigeria (FMBN). The NHF was established to mobilize long term funds and provide eligible contributors with access to relatively affordable housing finance. Generally, one needs to be an NHF contributor and have made at least six months of continuous contributions. FMBN also requires evidence of stable employment or for self-employed persons satisfactory evidence of regular income.
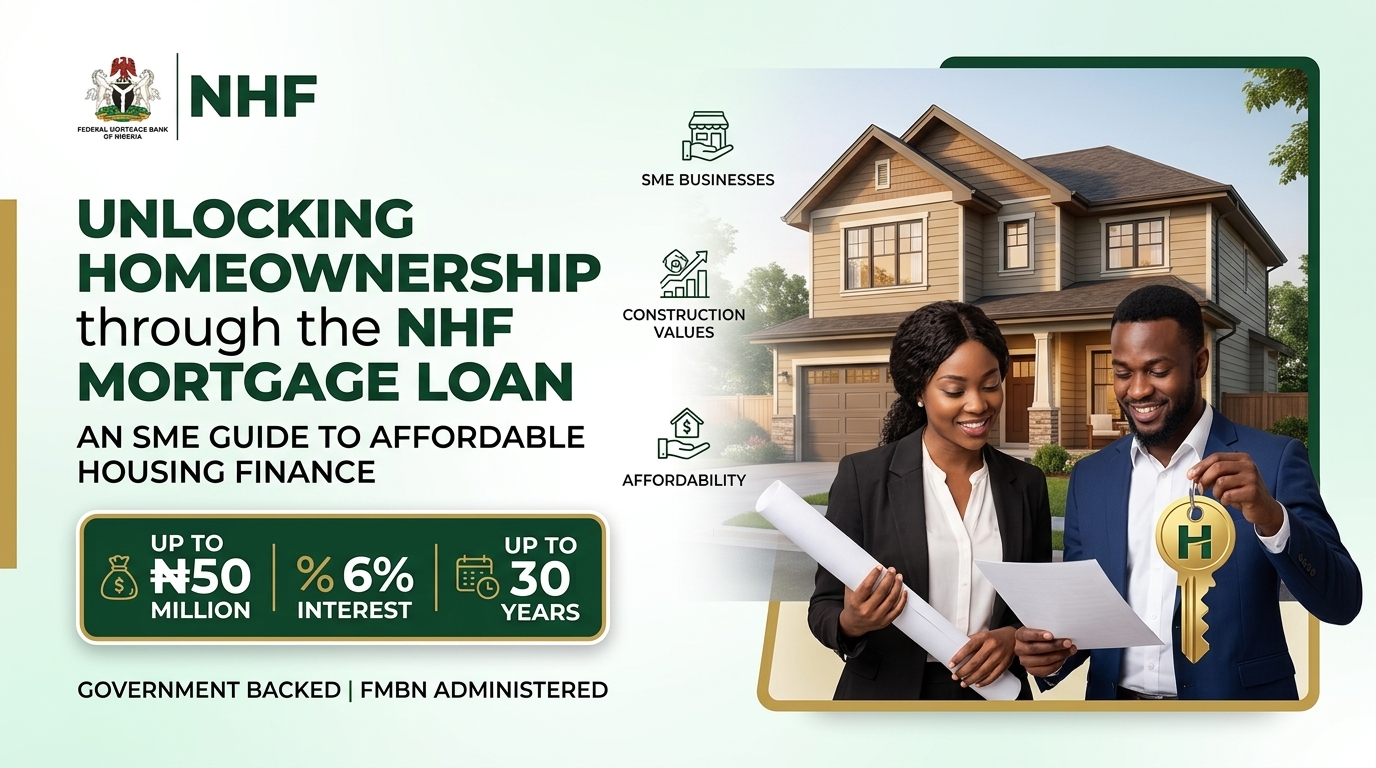
For Nigerians looking to own, build or improve a home, the National Housing Fund (NHF) Mortgage Loan remains one of the Federal Government’s most important housing finance channels. The Federal Mortgage Bank of Nigeria (FMBN) currently states that eligible NHF contributors can access up to ₦50 million at 6% interest for up to 30 years to buy, build, improve or renovate a home. Applicants generally need at least six months of continuous NHF contributions and must apply through an accredited Primary Mortgage Bank.
This is a significant opportunity but Nigerians should understand that it is not free money. The attraction is the relatively low 6% interest rate and long repayment period which can make home finance more manageable than conventional commercial lending.
The opportunity is particularly important given Nigeria’s housing challenge. New government data puts the 2025 housing deficit at approximately 14.9 million units. For SMEs, the implications are wider than homeownership because increased mortgage financing can stimulate construction, building materials, furniture, transport, professional services and other SME value chains. However, the informal economy and many self employed entrepreneurs may still face documentation, income verification and affordability barriers. Expanding access to finance for this segment will therefore be critical.
It is advicesable that interested participant should treat the NHF loan as a long term financial commitment not simply an opportunity to borrow. Confirm your eligibility, verify the property title and ensure the repayment obligation fits comfortably within your income.
Start by confirming your NHF contribution status and NHF number through FMBN. You can register or access your account through the FMBN online platform, then approach an accredited and licensed Primary Mortgage Bank (PMB) to submit the mortgage application and required property documents. The loan is secured against the property.
Visit NHF Mortgage Loan Information: NHF Mortgage Loan | FMBN
N.B. Ensure your NHF contribution status is verified and work only with accredited mortgage institutions. To make your journey easier, our Advisory Desk simplifies property acquisition by connecting you with structured mortgage options through our network of mortgage banks and brokers.
Speak with an advisor today by visiting our desk or calling 09030075977.
About the Author
Dr. Ozemoya Osikpemhi Amos Onoshoze Pedro is an accounting and finance scholar, researcher, and professional with over a decade of industry experience. Holding a Ph.D. in Accounting and Finance, his expertise spans corporate finance, strategic management, governance, and business innovation. He is passionate about producing research that bridges academic theory with practical business solutions, helping organizations achieve sustainable growth and financial excellence. You can reach him on LinkedIn