- October 28, 2026
Think Big, Measure Small: How Knowing Your Business in Detail Fuels Growth
The biggest growth opportunity in your business may not be something new. It may be something you already own and have never examined closely.
Harvard Business School’s Robert Kaplan has described a pattern found in nearly every customer profitability study: 15% to 20% of customers generate 100% or more of the profits.[1] If a small group produces all the profit, the rest are adding little, and some may be costing you money.
So here is an uncomfortable question. Can you name yours?
Meet Amaka, who sells ready-to-wear clothing in Lagos. Sales are rising, the phone keeps ringing, and she is about to rent a second shop. But ask her which dress earns the most profit, which customers come back, or how much cash is sitting on her shelves as unsold stock, and she will have to guess. A second shop will not fix those blind spots. It will copy them.
That is the case for thinking big and measuring small: keep the ambition, and break your business into small, measurable parts (what we call going granular) so that you decide from evidence, not instinct. Big dreams are built on small details. Follow Amaka through this article, and try each step on your own business.
| STAT SPOTLIGHT 15% to 20%: share of customers that generate 100% or more of profits in the studies Kaplan describes.[1] 39,654,385: MSMEs in Nigeria in 2020, of which 96.9% were micro enterprises (NBS figures cited by PwC).[2] 35%: share of the MSMEs surveyed by PwC that named inadequate access to finance as their number one challenge.[2] 28.3%: average maximum lending rate between January and June 2023, up from 27.8% in 2022.[2] At those prices, guessing is an expensive habit. |
Revenue feels good. Profit pays the bills. Amaka sells 60 dresses a month and assumes they are all doing well. When she finally lists each style with its price, direct cost and the time it takes to sell, she finds that her showpiece ankara gowns bring in the most money but tie up a lot of stock, while a plain everyday dress she barely promotes earns the most profit per naira invested.
Mike Michalowicz takes this thinking to its extreme in his book Profit First. Instead of the usual “Sales minus Expenses equals Profit”, he proposes “Sales minus Profit equals Expenses”: set the profit aside first and pay expenses from what remains.[3] You need not adopt his method, but the question behind it is worth asking: what does each product really leave you with? Do not just sell more. Understand the economics of selling more.
Try this today: list your top ten products, and next to each write the profit per unit, not the selling price.
“Young professionals” and “fashion lovers” are labels, not insight. Amaka’s real customers behave very differently. A boutique reseller buys in bulk, haggles hard and pays after 60 days. A group of regular individual buyers spend less each time but return every month. Event stylists show up once, in a hurry, and then disappear.
This is close to the 80/20 principle in Richard Koch’s book of that name, which holds that 80% of results flow from just 20% of the causes.[4] Treat the ratio as a rule of thumb to test against your own numbers, not a law. Keeping customers matters too. In a 1990 Harvard Business Review article, Frederick Reichheld and W. Earl Sasser Jr. argued that companies can boost profits by almost 100% by retaining just 5% more of their customers.[5] That is a decades-old US study, so use it as a prompt to measure your own repeat business, not as a forecast.
If you sell on credit, remember that a big customer who pays late can strain your cash more than a small one who pays in a week. Customer value is revenue, minus the cost and risk of serving that customer.
Try this today: mark your ten biggest customers as “pays on time”, “pays late” or “buys repeatedly”.
When sales disappoint, we reach for more advertising, more salespeople or bigger discounts. But the problem may be further down the road. Here is one month of Amaka’s WhatsApp and Instagram inquiries (an illustration):
| Stage | Customers | Share moving on |
| Enquiries | 1,000 | 20% become serious conversations |
| Serious conversations | 200 | 40% ask for a price or quote |
| Stage | Customers | Share moving on |
| Price quotes | 80 | 25% pay |
| Paid orders | 20 | Overall conversion: 2% |
A 2% conversion rate tells Amaka nothing on its own. The table shows where customers disappear: 80% of inquiries never become real conversations, and three in four quotes never turn into payment. Are her replies slow? Are her prices unclear? Does she follow up? Each leak needs a different cure, and more ads would simply pour more water into the same bucket. Sometimes the fastest route to more sales is converting more of the inquiries you already have.
Try this today: count last month’s inquiries, conversations, quotes and sales, and circle the biggest drop.
A healthy bank balance can mislead. It does not show what is already promised, or how much is trapped in stock and unpaid invoices.
Amaka pays her suppliers ₦10 million upfront for new stock, and sells ₦13 million of it to the boutique reseller, who pays in 60 days. On paper she makes ₦3 million. In practice, for those 60 days Amaka is financing her customer. This is the cash conversion cycle: how long stock sits before it sells, how long customers take to pay, and how quickly suppliers want paying. The JPMorgan Chase Institute studied about 597,000 US small businesses with Chase Business Banking accounts and found that the median business held only 27 cash buffer days. In other words, if its inflows stopped, it could pay its outflows from its cash balance for about 27 days.[6] That is US data from 2015, so Nigerian figures will differ, but the lesson travels well: a business can be profitable and still be thin on cash.
Now add borrowing. Suppose Amaka borrows ₦10 million for three months to buy stock, at the 28.3% average maximum lending rate reported by PwC for early 2023.[2] Using simple interest and ignoring fees, three months costs about ₦707,500, or 7.1% of the money borrowed. This is an illustration, not a CreditPRO rate.
| Illustration (90 days) | Gross margin on cost | Interest cost | Left before other costs |
| Everyday dress | 30% | 7.1% | About 22.9% |
| Slow-selling gown | 12% | 7.1% | About 4.9% |
Same loan, very different outcomes. That is the whole point of going granular: the cost of money lands hardest on your thinnest, slowest products. If your gap is the wait between delivering and getting paid, a tool such as invoice discounting can release cash against invoices you have already issued, and our loan calculator lets you test repayments before you commit. Capital accelerates a sound business model. It also accelerates a poorly managed one.
Try this today: write down your stock days, customer payment days and supplier payment days.
The most expensive problems rarely announce themselves. For Amaka it is ₦150,000 a month lost to damaged stock and unrecorded discounts. That sounds small. It is ₦1.8 million a year, and halving it would put ₦900,000 back in her pocket without winning a single new customer (illustrative figures).
Granular numbers also protect you from shiny distractions. A competitor launches a new range, a friend pitches a “quick return” investment, a customer asks for an extra service. Each idea competes for the same scarce money, people and time. Test it against what you know. Which product has proven demand? Which earns a real margin? Which eats resources and returns little? Sometimes the most profitable decision is to stop doing something. That is not timidity. It is disciplined capital allocation.
Try this today: pick your three biggest recurring costs and ask what changed in the last six months.
Sooner or later, many growing businesses need outside capital. Compare two owners each asking for ₦10 million. The first says: “Sales are rising and we need to expand.” The second says: “We have a confirmed larger order, we need this much stock, the expected gross margin is this, our cash cycle is this, and here is how repayment will come from collections.”
Neither is guaranteed to succeed. Demand can shift, customers can pay late and costs can climb. But the second owner can test assumptions and spot trouble before signing for the debt, and can explain the need clearly to a lender. With the average maximum lending rate at 28.3% in early 2023, that clarity is worth a great deal.[2] Borrowing should support a decision whose economics you have already examined. It should never replace understanding your business.
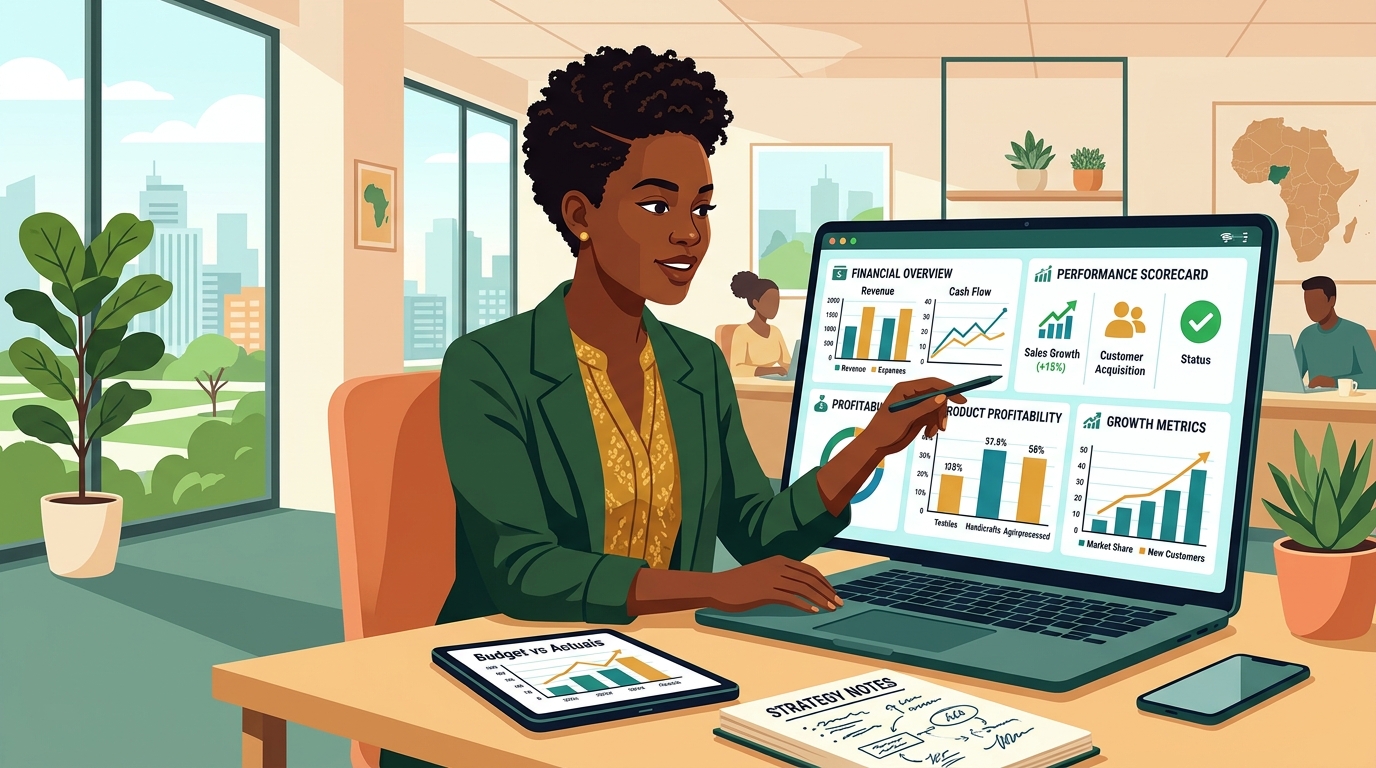
You do not need expensive software. A spreadsheet and a 30-minute monthly routine are enough to begin. Copy this scorecard into Excel or Google Sheets and fill in one row per product (the sample row is illustrative):
| Product | Units sold | Selling price | Direct cost | Profit per unit | Days to sell | Days to get paid |
| Everyday dress | 25 | ₦18,200 | ₦14,000 | ₦4,200 | 30 | 0 |
| (your product) | ||||||
| (your product) |
Each month, ask three questions: What is happening? Why is it happening? What will we do about it, who will do it, and when will we check?
YOUR 7-DAY GO GRANULAR SPRINT
Day 1: List your top 10 products with the profit on each.
Day 2: List your top 10 customers. Mark who pays late and who buys repeatedly.
Day 3: Count inquiries, conversations, quotes and sales. Find the biggest drop.
Day 4: Write down stock days, customer payment days and supplier payment days.
Day 5: Find your three biggest recurring costs and what changed.
Day 6: Choose one thing to stop, one to fix and one to grow.
Day 7: Book a 30-minute monthly review in your diary. Keep it.
Businesses often struggle after expanding because their operations grew faster than their understanding of them. More customers bring more service demands, more stock brings more working capital needs, and more branches bring more room for inconsistency and leakage. Expansion magnifies whatever is already there, good or bad. Thinking big and measuring small offers another path:
understand it first, then improve, standardize and scale. It may look slower. It can also help you avoid costly mistakes, which matters when borrowing is expensive.[2]
When we speak with business owners about financing, the conversations that go best are the ones where the owner can explain how the business makes money and how the funding will make more. That clarity does not come from a bigger business. It comes from a better-understood one. You can see everything we offer on our loan offerings page, or talk to us through the contact page.
Final Thoughts: Think Big. Measure Small. Then Grow Wide.
Before opening another branch, study the one you have. Before adding another product, learn the profit on the ones you sell. Before borrowing to expand, work out how the extra money will turn into cash to repay it. Sustainable growth is not about becoming bigger. It is about becoming better at what you do.
So here is your challenge: start the 7-day sprint tomorrow, and run your next purchase through our loan calculator before you commit. What part of your business do you need to understand more deeply before you try to grow it?
Note: Amaka is fictional. All naira figures, the inquiry funnel, the scorecard sample row and the loan example (simple interest, no fees, 28.3% used only as a reference rate) are illustrations, not CreditPRO rates or market data. Books [3] and [4] are print publications.
About the Author
Anthony Jiboye is the Head of Growth and Customer Experience at CreditPRO Finance Company Limited. With a proven track record in driving business expansion, customer retention strategies, and service excellence, Anthony leads CreditPRO’s growth initiatives to deliver seamless, customer-centric financial solutions. He is passionate about scaling innovative financial products, enhancing user journeys, and empowering businesses across Nigeria to access reliable funding and growth opportunities.