- November 16, 2026
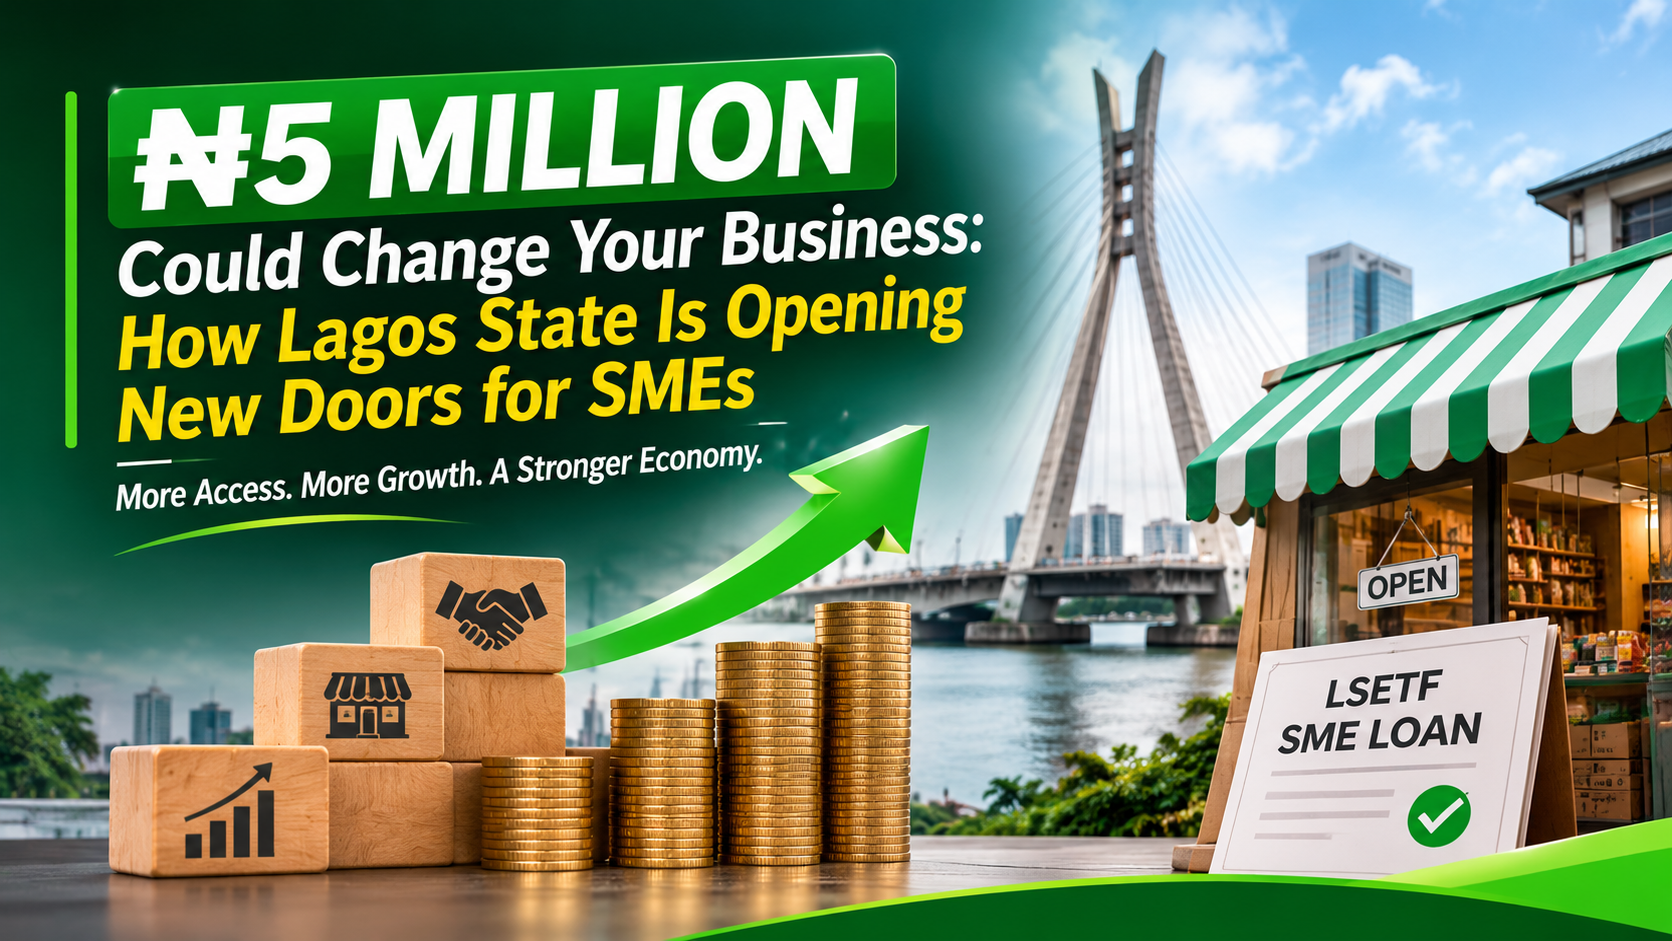
For many entrepreneurs in Nigeria, the biggest obstacle to business growth is not a lack of ideas, customers or determination, but the lack of affordable capital. This is the financing dilemma facing thousands of SMEs across Nigeria, and it is against this backdrop that the Lagos State Employment Trust Fund (LSETF) provides an opportunity for eligible small and medium-sized businesses to access loans of up to ₦5 million. The programme is designed to improve access to finance, support business expansion and create employment opportunities.
According to LSETF’s published SME loan programme, eligible businesses can access between ₦500,000 and ₦5 million, with a stated interest rate of 9% per annum and a repayment period of 24 to 36 months.
However, the programme is specifically designed for eligible businesses operating in Lagos, with business owners required to be residents of Lagos State. Applicants must also meet other requirements, including business registration and evidence of business operations.
Beyond the headline figure, the bigger question is this: Can affordable financing transform the growth prospects of Nigerian SMEs and improve the welfare of the larger society?
Small and medium-sized enterprises are widely recognized as the backbone of economic development, as they provide employment, stimulate innovation, support local production and contribute to the development of communities. Yet, many Nigerian SMEs remain trapped in a cycle of low capital, limited production capacity and slow business growth.
One of the major reasons is the difficulty of accessing affordable financing, since commercial banks often require collateral, detailed financial records, credit histories and other conditions that many small businesses struggle to satisfy. Even when financing is available, high interest rates and short repayment periods can make borrowing unattractive or financially dangerous.
Consider a small food-processing business in Lagos that receives regular orders from supermarkets. The business owner may need ₦3 million to purchase processing equipment, increase production and meet growing demand. However, without access to affordable financing, the business may continue operating below capacity, lose customers to competitors or remain unable to employ additional workers.
This is not merely a problem for individual businesses; rather, it is a structural challenge affecting Nigeria’s productive capacity. This financing gap prevents viable businesses from expanding, discourages investment, limits job creation and weakens the contribution of SMEs to economic growth.
The LSETF loan programme seeks to address this challenge by providing eligible businesses with access to financing that may be more affordable and accessible than conventional commercial loans.
The significance of the initiative lies in its attempt to bridge the gap between businesses with growth potential and the financial resources required to realize that potential.
Access to financing can fundamentally change the trajectory of a small business.
When an entrepreneur obtains financing on reasonable terms, the business can purchase equipment, increase inventory, improve operational efficiency, expand its customer base and employ additional workers.
For instance, a small manufacturing business that obtains ₦5 million to purchase production equipment may be able to increase output, reduce production costs and meet larger customer orders. The resulting increase in revenue may enable the business to repay the loan while retaining sufficient funds for further expansion.
However, the implications extend beyond the individual business, as affordable financing can stimulate economic activity across multiple sectors. A growing manufacturing business purchases raw materials from suppliers, employs workers, pays transporters and distributes products through retailers. Each of these activities generates income and supports other businesses, thereby creating a multiplier effect within the economy.
For Nigerian SMEs, the LSETF initiative presents an opportunity to move from subsistence-level operations towards structured, sustainable and competitive enterprises.
Nevertheless, access to credit must be accompanied by sound financial management, as borrowing without a clear investment plan may expose businesses to repayment difficulties, particularly in an environment characterized by inflation, fluctuating exchange rates and uncertain consumer demand.
The implication is therefore twofold: affordable financing can accelerate business growth, but responsible borrowing and effective management are essential to converting that financing into sustainable economic value.
The LSETF programme highlights an important principle of economic policy: government intervention in SME financing should address the structural barriers preventing businesses from accessing capital.
The initiative is an example of how subnational governments can use targeted financing programmes to support entrepreneurship, employment and economic development.
However, the effectiveness of such programmes depends on more than the amount of money allocated.
First, government must ensure that financing reaches viable businesses rather than being distributed primarily through political connections or administrative discretion. Transparent eligibility criteria, objective assessments and clear application procedures are essential to maintaining public confidence.
Second, policymakers must recognize that SMEs operate within a broader business environment. Access to finance alone cannot compensate for unreliable electricity, poor infrastructure, high transportation costs, inconsistent policies and excessive regulatory burdens.
A business that receives financing but continues to face prohibitive operating costs may struggle to achieve sustainable growth.
Third, government should strengthen partnerships between public financing institutions, commercial banks, business development organizations and private investors. Such partnerships can improve credit assessment, reduce financing risks and expand the reach of funding programmes.
Finally, SME financing policies should be evaluated based on measurable economic outcomes. These include the number of businesses supported, jobs created, businesses that remain operational, increases in business turnover and the proportion of loans successfully repaid.
The policy implication is clear: government should treat SME financing as an investment in productive capacity, not merely as a financial assistance programme.
The ultimate objective should be to create an environment in which viable businesses can grow, employ more people and eventually access commercial financing without depending indefinitely on government intervention.
For the LSETF initiative to achieve its intended objectives, both business owners and policymakers must take deliberate action.
For SMEs, the first recommendation is to develop a clear financing strategy before applying for a loan.
Business owners should identify the specific purpose of the financing, estimate the expected increase in revenue, calculate operating costs and determine whether the business can comfortably meet its repayment obligations.
A loan should ideally finance productive activities capable of generating additional cash flow. Using borrowed funds to purchase equipment, expand inventory or improve production capacity may create long-term value, provided the investment is commercially viable.
Also, entrepreneurs should assess the total cost of borrowing. The LSETF’s published SME Loan Programme page currently states an interest rate of 9% per annum, while its online application portal FAQ states 5% per annum. These published figures differ, so applicants should confirm the applicable interest rate, fees, repayment schedule and current availability directly with LSETF before making a borrowing decision.
The programme also specifies a 5% equity contribution. This means that applicants should make provision for their required contribution in addition to the amount they intend to borrow.
Furthermore, prospective applicants should understand the programme’s eligibility requirements. These include operating a business in Lagos State, being a Lagos State resident, having a business that has operated for at least one year and possessing valid business registration documents. Other application requirements include relevant identification, tax information, business bank statements and guarantor documentation. Applicants should consult LSETF’s official programme guidelines for the complete and current requirements.
For government, the recommendation is to expand access to financing while strengthening monitoring, transparency and business development support.
Financing programmes should be accompanied by financial literacy training, business advisory services, market access support and practical guidance on business formalization.
Government should also consider the diverse needs of SMEs. A small retail business may require short-term working capital, while a manufacturing enterprise may require longer-term financing for equipment and infrastructure.
A one-size-fits-all financing model may not adequately address these different needs.
Ultimately, the success of SME financing programmes should be measured not by the volume of money disbursed, but by the number of businesses that become stronger, more productive and capable of sustaining employment.
The benefits of affordable SME financing extend far beyond the entrepreneurs who receive the loans.
When SMEs grow, they create employment opportunities for young people, women and other members of the workforce. Increased employment reduces household financial vulnerability and improves the ability of families to afford education, healthcare, food and other essential needs.
Growing businesses also strengthen local supply chains. A manufacturing enterprise purchases raw materials from farmers and suppliers, engages transport operators, employs workers and distributes products through retailers. These relationships spread economic benefits across communities.
Furthermore, increased production can improve the availability of locally manufactured goods, reduce dependence on imported products and strengthen domestic economic activity.
As businesses expand, they may also generate higher tax revenues for government, which can support public infrastructure, education, healthcare and other essential services.
There is also an important social dimension. When people have access to sustainable employment and opportunities to build businesses, communities become more economically resilient. The likelihood of extreme financial hardship may decline, while opportunities for upward social mobility improve.
However, these benefits are not automatic, as they depend on financing reaching viable businesses, investments generating productive returns and the wider business environment supporting sustainable growth.
The real value of the LSETF initiative is therefore not simply the possibility of an entrepreneur receiving ₦5 million. It is the possibility that this financing could help a business expand, employ additional workers, support other businesses and improve the livelihoods of families and communities.
Ultimately, access to capital may open the door, but how effectively a business manages and deploys that capital will determine the value it creates.
About the Author
Dr. Ozemoya Osikpemhi Amos Onoshoze Pedro is an accounting and finance scholar, researcher, and professional with over a decade of industry experience. Holding a Ph.D. in Accounting and Finance, his expertise spans corporate finance, strategic management, governance, and business innovation. He is passionate about producing research that bridges academic theory with practical business solutions, helping organizations achieve sustainable growth and financial excellence. You can reach him on LinkedIn